COBRA Dental Insurance: Keeping Your Work Dental Plan After a Job Ends

Reviewed by Russell Noga, Licensed Insurance Broker — Last updated November 12, 2026

COBRA dental insurance lets you, your spouse and your children keep the same dental plan you had at work, usually for 18 months, by paying the full premium plus up to a 2% fee. Federal COBRA applies to employers with 20 or more employees, you get at least 60 days to sign up, and the first payment is not due until 45 days after you elect.

2027 by the Numbers

20+

employees an employer needs for federal COBRA to apply (U.S. Dept. of Labor)

60 days

minimum window to elect COBRA after your notice or loss of coverage (DOL)

102%

most a plan can charge of the full cost of coverage (DOL)

18 / 36

months of continuation after a job loss / after divorce or a worker’s death (DOL)

When a job ends, work dental coverage often stops at the end of the month. COBRA, a 1985 federal law, keeps that same plan, network and benefit year running while you decide what comes next.

Below: the deadlines, what the plan can charge, keeping dental on its own, and COBRA side by side with an individual dental plan, a spouse’s plan and the Marketplace.
Compare Dental Plans Before Your COBRA Deadline

The COBRA Dental Clock, From Last Day to First Payment

COBRA dental insurance deadlines from job loss to election and first premium payment

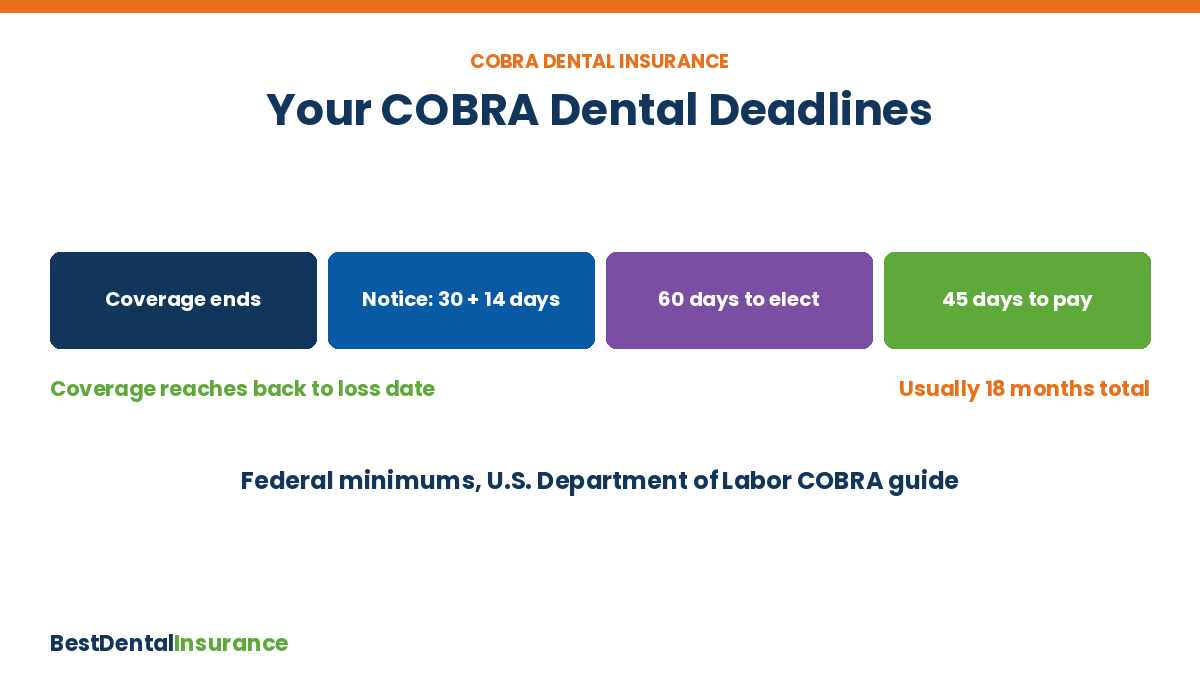
COBRA runs on federal minimum deadlines from the Department of Labor (DOL). A plan can give more time, never less.

1

Employer tells the plan. Within 30 days after a job ends, hours are cut, the worker dies or becomes entitled to Medicare.

2

Plan mails your election notice. Within 14 days after it hears about the event. For divorce, separation or a child aging off the plan, the family must report it, with at least 60 days allowed.

3

You decide. You have at least 60 days, counted from the later of the notice date or the day coverage would end.

4

You pay. No money is due when you elect. The first premium is due no sooner than 45 days after you elect, and later payments get at least a 30-day grace period.

Timing detail: The DOL says COBRA coverage is retroactive to the day you lost your job-based plan, so electing inside the window can cover care received in the meantime. You owe premiums back to that date.

Dental Insurance Quotes

Call a Licensed Agent Now

Compare dental plans for individuals, families and seniors from several insurance companies in one call.

☎ 1-833-667-3396

TTY users 711  |  Mon–Fri: 8am–9pm ET

No obligation to enroll

Who Qualifies and How Many Months Dental Continues

Federal COBRA covers private employers that had at least 20 employees on more than half of their typical business days last year, plus state and local government plans. Part-timers count as a fraction of a worker. Federal and church plans are outside it.

What happenedWho can electMaximum months
Job ends for any reason except gross misconduct, or hours cutWorker, spouse, children18
Same, plus a Social Security disability ruling in the first 60 daysEach family member on the plan29
Worker dies, divorce or legal separation, or worker becomes entitled to MedicareSpouse and children36
Child loses dependent status under plan rulesThat child36
Second qualifying event during the first 18 monthsSpouse and childrenUp to 36 in total

Source: U.S. Department of Labor COBRA guide. Coverage can end early for late premiums, if the employer drops all group health plans, or if you gain other group coverage.

Many states have their own continuation laws, often called mini-COBRA, for employers with fewer than 20 workers. Whether they include dental, and for how long, varies by state.

Can You Keep Just the Dental Plan?

Often, yes. IRS COBRA rules give every qualified family member an independent election. When the employer’s dental benefit is its own plan, apart from medical, it is usually a separate line on the election form. If plan documents bundle dental with medical, you may have to take both.

Only what you had. COBRA continues plans you were enrolled in the day before the event. Skipped dental at work? You cannot add it now.

Same plan, same rules. Coverage must match what current employees on that plan get, network included.

Each person decides. A spouse can keep dental while the former worker drops it.

Open enrollment still applies. People on COBRA get the same yearly plan-change chance active employees get.

What COBRA Dental Costs and What You Keep for the Money

COBRA dental insurance compared with a new individual dental plan

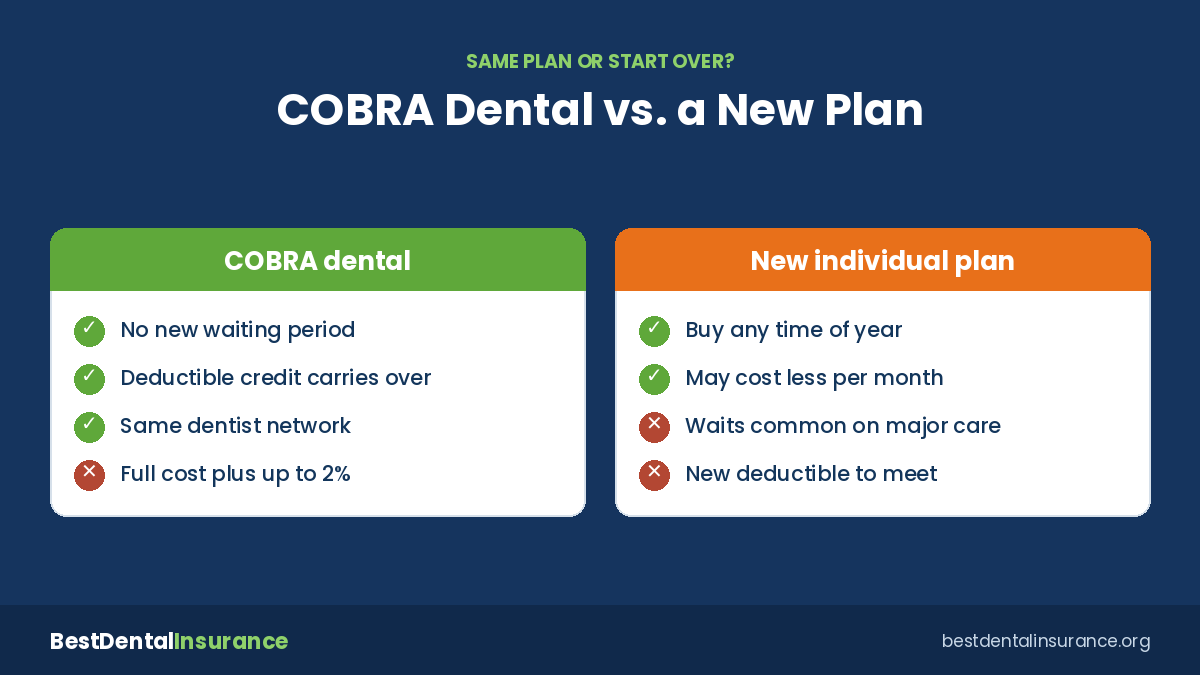
On COBRA you pay the whole premium, including any share your employer covered, plus up to 2% for administration. During a disability extension past month 18, the cap rises to 150%. Your election notice lists the monthly price.

The price buys continuity. Under Treasury COBRA regulations, what you already paid toward this year’s deductible still counts, and benefits used count against the same annual and lifetime limits. Because it is the same plan, no new waiting period starts.

Math to do first: Multiply the monthly COBRA price by the months you expect to need it and compare that total with dental work already planned. A crown due soon can tip the answer toward COBRA; a year of checkups alone often does not.

Find & Compare Plans Online

Speak with a licensed insurance agent

1-833-667-3396TTY 711

Mon-Fri: 8am-9pm ET

COBRA Dental vs. an Individual, Spouse's or Marketplace Plan

Each option has its own sign-up deadline, so line up the dates before your COBRA window closes.

OptionWhen you can joinWaiting periodsBest fit
COBRA dentalAt least 60 days to elect; coverage reaches back to the loss dateNone new; same plan continuesTreatment in progress or planned soon
Individual dental planAny time of year with most carriersCommon for basic and major work; varies by plan and stateMostly preventive needs, lower budget
Spouse’s employer planOften within 30 days of losing other coverage; stand-alone dental may follow its own rulesPer that plan’s termsSpouse has a strong plan at a low added cost
Marketplace dental60 days before or after losing job coverageAdult plans may have them; pediatric dental cannotBuying a Marketplace health plan anyway

Sources: U.S. Department of Labor COBRA guide and HealthCare.gov. In HealthCare.gov states, Marketplace dental generally requires a Marketplace health plan too; some state exchanges sell dental alone.

For coverage that starts fast, see dental plans with no waiting period and our Marketplace dental insurance guide. Dropping COBRA early does not open a Marketplace enrollment window, though most individual dental plans sell year-round.

If you have two plans: When you also have active or dependent coverage, that plan pays first and COBRA pays second. See secondary dental insurance.

COBRA Dental Near 65 and When Medicare Enters the Picture

Original Medicare does not cover most routine dental care, so many people near 65 want to keep a work dental plan. COBRA can help, with two catches.

Order of enrollment matters. If Medicare Part A or B starts after you elect COBRA, the plan may end COBRA. If Medicare started first, it cannot end it for that reason.

COBRA does not protect Part B timing. Social Security’s 8-month Part B special enrollment period after work ends is based on current employment, and COBRA does not count. Waiting can bring a Part B late-enrollment penalty.

Spouses can get 36 months. When the worker becomes entitled to Medicare and the spouse loses coverage, the spouse and children can elect COBRA for up to 36 months.

Some Medicare Advantage plans include dental benefits that vary by plan. Before ending COBRA, confirm when new dental coverage starts and check dental open enrollment periods.

Bottom Line

COBRA dental keeps the plan you already know, with no fresh waiting period and credit for this year’s deductible, at the full premium plus up to 2%. Use the 60-day window to price an individual plan, a spouse’s plan and the Marketplace, and elect before the deadline if treatment is underway or coming soon.

See individual dental plans and prices in your ZIP code

COBRA Dental Insurance — Frequently Asked Questions

➤ How long do I have to sign up for COBRA dental?

At least 60 days from the later of the date on your election notice or the date your coverage would end. Your plan can allow more time, but not less.

➤ Is COBRA dental cheaper than buying my own plan?

Not always. COBRA charges the full plan cost plus up to 2%, while an individual plan may cost less but often has waiting periods for fillings and crowns.

➤ Can my ex-spouse stay on my dental plan after a divorce?

Yes, through COBRA, for up to 36 months, if the plan is told within its deadline, which must be at least 60 days.

➤ What happens if I miss a COBRA dental payment?

Plans must allow at least a 30-day grace period on payments after the first. Miss that and the plan can end coverage for good.

➤ Does COBRA dental restart my annual maximum?

No. It is the same plan, so benefits used this year still count toward the annual maximum, and deductible payments stay credited.

➤ My employer has 12 workers. Can I still keep dental?

Federal COBRA does not apply, but many states have mini-COBRA laws for small employers. Whether dental is included depends on your state and plan.

➤ Can I switch to a different dental plan while on COBRA?

Generally only during the employer’s open enrollment, when people on COBRA get the same choices as current employees.

➤ Will a new job’s dental plan end my COBRA?

It can. Gaining group coverage after you elect COBRA lets the plan end COBRA, so confirm the new plan’s start date and any waiting period first.

Dental Insurance Quotes

Call a Licensed Agent Now

Compare dental plans for individuals, families and seniors from several insurance companies in one call.

☎ 1-833-667-3396

TTY users 711  |  Mon–Fri: 8am–9pm ET

No obligation to enroll

Find & Compare Plans Online

Speak with a licensed insurance agent

1-833-667-3396TTY 711

Mon-Fri: 8am-9pm ET

ZRN Health & Financial Services, LLC, a Texas limited liability company